Read next
The latest news, updates and expert views for ambitious, high-achieving and purpose-driven homeowners and property entrepreneurs.


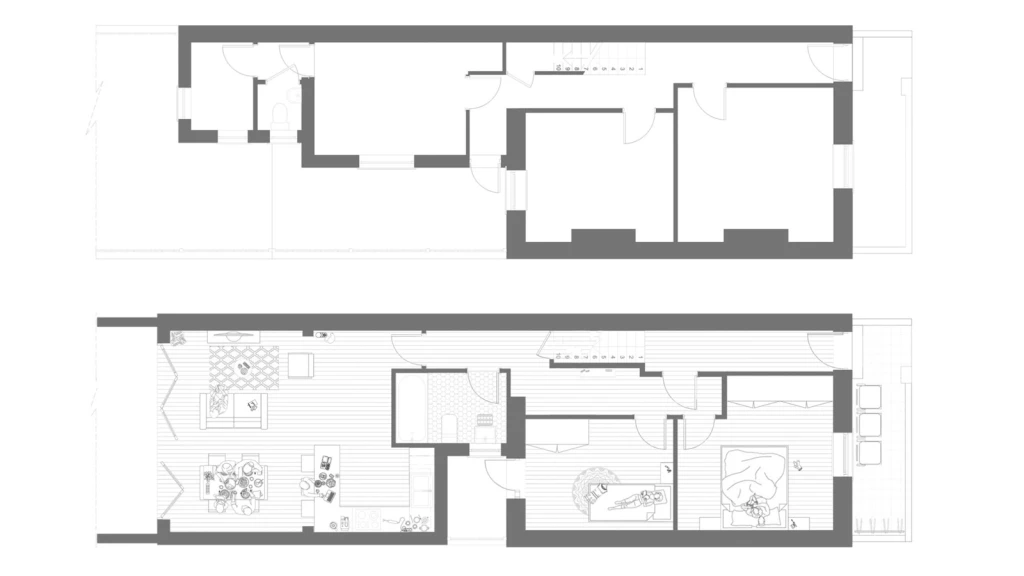
Imagine arriving at an architect’s office with a London house plan and a straightforward request: fit in as many lettable bedrooms as possible.
You have marked a possible room beside the kitchen, another in the reception space and perhaps one more in the loft. Every additional bedroom appears to strengthen the investment.
Before those lines become a design brief, several questions need answering.
Does the property need HMO (House in Multiple Occupation) planning permission?
Would local policy support the conversion?
And how much accommodation remains once shared facilities, daylight, circulation and effects on neighbours have been properly considered?
Those answers should shape the bedroom count.
In this article, I will explain when HMO planning permission is needed in London, what councils assess and how informed design decisions can strengthen your planning application.
The starting point is how many people live in the property, how they form households and which facilities they share. England’s use class order distinguishes between ordinary homes, small HMOs and larger shared properties:
Class C3 covers dwellinghouses, including homes occupied by a person or family, and certain groups of up to six people living as a single household.
Class C4 covers small HMOs occupied by up to six residents, using the Housing Act 2004 definition.
Larger HMOs, with more than six residents, are normally sui generis, meaning a use in a class of its own.
Under the Use Classes Order 1987, as amended, Class C4 draws on the Housing Act 2004 definition of an HMO. A single person, a couple or members of the same family can form a household. Unrelated people do not become one household simply because they sign a joint tenancy.
This explains why properties with the same number of residents can have different planning uses. A couple sharing a kitchen with two unrelated friends would normally occupy a C4 HMO: four residents forming three households. Replace those friends with the couple’s children and the property would ordinarily remain a C3 family home. Seven unrelated students sharing a house would normally occupy a sui generis HMO.
The practical rule is to count people and households, not bedrooms, then establish how the accommodation is used.
Shared facilities alone do not make accommodation an HMO: its use and operation determine the planning classification. Short-term let aparthotels and serviced apartments generally fall within Class C1 when operated as commercial hotels.
Co-living provides another form of shared accommodation, combining private rooms with professionally managed communal spaces. It has no statutory use class, although large purpose-built London schemes are normally sui generis and assessed under London Plan Policy H16. The route to planning permission for co-living depends on the scheme’s scale, layout and management.
In London, one house may qualify for conversion into a small HMO under permitted development, while another may need planning permission for the same proposal.
Establishing which route applies before you commit to a layout or rental forecast can change your HMO investment decision. The following five situations explain where your property stands.
Class L of the General Permitted Development Order allows changes between a family house (Class C3) and a small HMO for three to six people (Class C4) without a planning application, provided the relevant rights remain available. There is no prior approval stage: national legislation grants the permission.
To establish whether you can use this route, confirm the property’s lawful C3 use, check previous planning conditions and consult the council’s current Article 4 map. Where the right remains available, a lawful development certificate for the proposed use can provide useful evidence for a future buyer or lender.
Class L covers the change of use itself. Any extensions, dormers or subdivision into separate homes need their own assessment.
In many parts of London, councils have removed the permitted development right to convert a family house into a small HMO through an Article 4 direction. Where an operative direction covers your property and the proposed change, you must apply for planning permission. The conversion remains possible, but its acceptability must be demonstrated through the design and planning case.
The first step is therefore to check exactly what the direction covers and when it took effect. Its wording establishes which rights have been removed; its boundary determines whether your property is affected. Timing matters too: an announced direction may not yet be in force, while a C4 use lawfully established before it took effect does not automatically need fresh permission.
A proposal to change a family house into an HMO for seven or more residents requires planning permission for a sui generis use, whether or not an Article 4 direction applies.
Count residents and households, not bedrooms. Six bedrooms occupied by seven unrelated people do not fall within C4. An established lawful large HMO may have a different starting position.
An existing HMO’s lawful use does not give it unlimited scope to grow. Start with its decision notice and any lawful development certificate to establish what has been authorised, including any occupancy limits.
The proposed increase must then be assessed against that starting point. Moving a C4 HMO from six residents to eight takes it outside C4 and will require planning permission. For an already lawful large HMO, an additional resident does not automatically change the planning use: the question is whether the increase materially alters its scale, character or effects.
Any condition restricting occupancy must still be addressed, even where the increase would not otherwise amount to a material change of use. Likewise, extensions, loft conversions and new self-contained units need separate assessment; the existing HMO use does not establish permission for those changes.
If your property is already operating as an HMO without planning permission, first check whether permission was required when the use began.
The absence of a planning decision does not, by itself, make the use unlawful.However, if permission was required and the HMO use remains unauthorised, the council may issue an enforcement notice requiring it to stop, putting your rental income at risk.
Failing to comply with that notice is a criminal offence carrying an unlimited fine. Following a conviction, the council may also seek confiscation of the financial benefit obtained from the breach.
There are two main ways to address an existing HMO’s unresolved planning status:
Choosing the right route starts with the property’s history. An architect or town planner experienced in HMOs can advise whether to seek a certificate of lawfulness, retrospective permission or part-retrospective permission incorporating proposed changes.
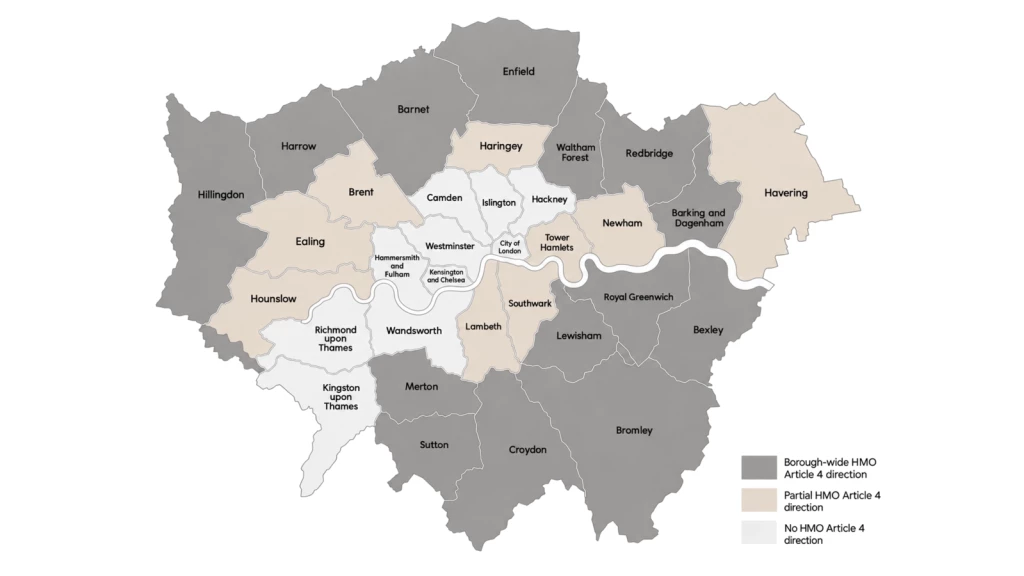
As of October 2026, the following London boroughs had borough-wide HMO Article 4 directions in force, meaning you will need planning permission to convert a family house into a small HMO for three to six people:
Barking and Dagenham
Barnet
Bexley
Bromley
Croydon
Enfield
Harrow
Hillingdon
Lewisham
Merton
Redbridge
Royal Greenwich
Sutton
Waltham Forest
In the following boroughs, directions covered only part of the area:
Brent
Ealing
Haringey
Havering
Hounslow
Lambeth
Newham
Southwark
Tower Hamlets
Where a direction covers only part of a borough, check the council’s Article 4 map to see whether your property falls within its boundary. The borough name alone will not tell you whether permission is required.
No. A licence can confirm that a property is suitable for occupation under housing law while leaving its planning position unresolved. Both matters may sit with the same council, but they are assessed under separate legislation. A licence therefore offers no protection against enforcement of an unauthorised planning use.
To understand what has actually been established, look at the question each consent answers:
Planning permission: are the proposed use and building works acceptable at this address?
Lawful development certificate: is the existing or proposed use lawful in planning terms?
HMO licence: is the property suitable and properly managed for the stated number of occupiers under housing law?
Building Regulations approval: do the works meet technical requirements, including fire safety, structure, sound insulation and drainage?
Mandatory licensing generally applies to HMOs occupied by five or more people forming two or more households and sharing facilities, subject to exemptions. Smaller HMOs may also need a licence under an additional licensing scheme, so check the requirements for the address.
Room sizes make the distinction between licensing and planning particularly clear. National licensing minimums for sleeping rooms are:
6.51 sqm for one person aged over 10;
10.22 sqm for two people aged over 10;
4.64 sqm for one child under 10.
These figures establish minimum sleeping room areas for licensing purposes. They do not settle whether the accommodation is acceptable for planning. The council may require larger rooms and will also consider their shape, layout, daylight and outlook.
The regimes are enforced separately. A licence cannot cure a planning breach, planning permission cannot replace a licence, and one property can face both sets of consequences at once.
An enforcement notice can require an unauthorised HMO use to stop, putting its rental income at risk. Any appeal must be made before the notice takes effect.
Failing to comply with an enforcement notice is a criminal offence, punishable by an unlimited fine. The court must take account of any financial benefit from the offence.
Some London councils, Camden among them, say they will seek confiscation orders under the Proceeds of Crime Act 2002 to recover the proceeds of offending.
Breaching a planning condition, such as an occupancy cap, can lead to a breach of condition notice. Since 25 April 2024, failing to comply with one has also carried an unlimited fine.
In November 2018, joint action by Brent and Harrow councils resulted in a £1.5 million confiscation order against a landlord who continued renting unlawfully converted properties despite planning enforcement notices. One contained eight cramped bedsits.
Alongside the confiscation order under the Proceeds of Crime Act, the landlord received a £12,000 fine and was ordered to pay prosecution costs. The court allowed three months to pay or face nine years in prison.
A year later, a Hillingdon landlord was ordered to surrender £406,712 under the same legislation after converting a family house into a large HMO without planning permission. Despite an enforcement notice requiring its return to a single home, the landlord continued accommodating 15 tenants across the house and an outbuilding.
A £20,000 fine and £4,019 in costs brought the total to more than £430,000. The court gave the landlord three months to pay or face five years in prison, with imprisonment leaving the debt outstanding.
Controlling or managing a licensable HMO without a licence is a criminal offence, punishable on conviction by an unlimited fine.
Councils can instead impose a civil penalty of up to £40,000 for offences committed from 1 May 2026, up from £30,000.
Tenants or the council can apply for a rent repayment order. Under the rules introduced on 1 May 2026, an order can cover up to two years’ rent, double the previous maximum. Earlier offences remain subject to the previous rules.
A conviction for a qualifying offence can lead to a banning order, preventing the landlord from letting housing in England.
The risk is greater than a fine: you may lose the right to continue the HMO use and be ordered to surrender the income earned from the offence. Establishing that your proposal can meet both planning and licensing requirements should therefore be part of the investment decision, before you commit to the property or conversion.
The planning policies for HMO conversions in London work in layers, and every layer counts.
The starting point is the development plan. In London, that means the London Plan, your borough’s Local Plan and any neighbourhood plan covering the street. The council must decide your application in line with that plan unless other material considerations point the other way.
National policy is the most important of those considerations. The NPPF 2026, published on 17 August 2026, applied to decisions from the day it came out.
It also changed how much weight older local policies carry. Where a local policy clashes with the Framework’s decision-making policies, it now carries very limited weight. A policy that is simply old, but still consistent, keeps its full force.
S4 Principle of development within settlements: development should be approved unless its benefits are substantially outweighed by adverse effects.
HO7 Meeting the need for homes: substantial weight goes to homes that meet evidenced accommodation needs, not an owner’s target yield.
DP3 Key principles for well-designed places: unjustified conflict with local design standards should lead to refusal.
P3 Living conditions and pollution: residents need adequate light and protection from noise, and neighbours must not lose unacceptable daylight.
TR4 Street design, access and parking: secure, usable cycle parking and parking suited to the location.
F7 Ensuring development is safe from flooding: an exemption from the sequential test is not an exemption from proving the scheme is safe.
H9 Ensuring the best use of stock: HMOs of a reasonable standard should generally be protected, but the policy creates no right to convert.
D6 Housing quality and standards: its layout, daylight and refuse-storage requirements apply to HMO decisions.
D12 Fire safety: Part A applies to all development, however small.
T5 Cycling and T6 Car parking: accessible cycle storage, and car-free development as the starting point in well-connected places.
The borough’s own adopted Local Plan is usually where the decisive tests sit. Check it for:
Draft Local Plan policies must also be considered, but their weight depends on how advanced the plan is, unresolved objections and consistency with national policy. Boroughs differ sharply, so a scheme acceptable in one can fail in the next.
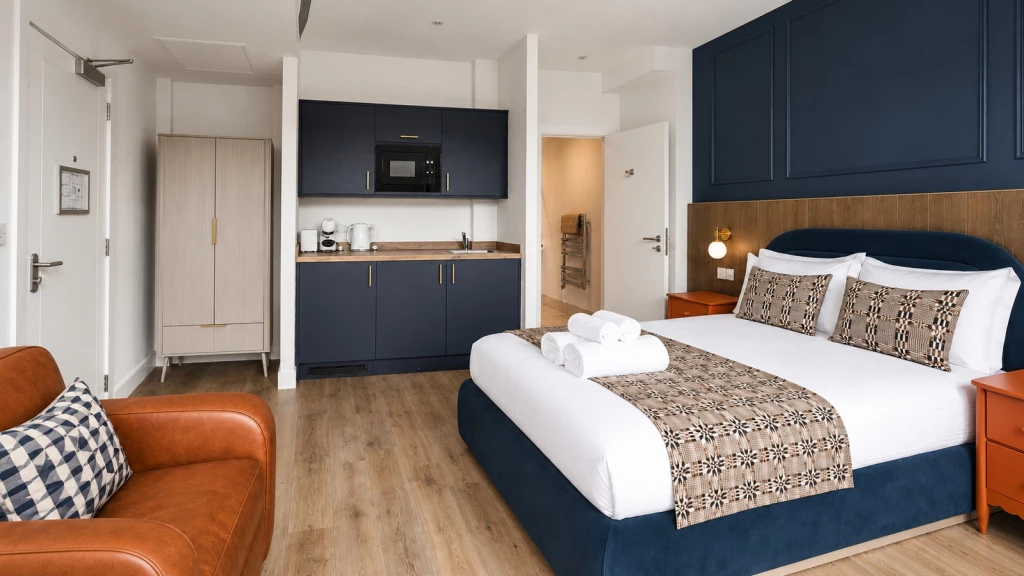
Once the route is clear, the application turns on whether the design shows acceptable living conditions and impacts. The reasoning should run in a line: the design choice, its effect on residents, neighbours or operation, the policy test, the evidence, and any remaining harm weighed against the benefits.
Good drawings cannot overcome every objection. A family housing policy, a concentration test or a flood constraint may decide a proposal before anyone looks at the layout. Design can, however, turn a marginal scheme into an acceptable one, or show that an arrangement already works.
Under HO7, evidence of need for shared housing helps, but local policies protecting family homes can point the other way. Check which of those tests your borough applies before you fix a layout.
There is no single London-wide set of HMO planning room sizes. Your architects and town planners will develop the HMO conversion around your council’s policies and space standards, checking:
minimum bedroom areas for one or two residents;
different requirements where cooking facilities are inside the bedroom;
kitchen, dining and living space sized for the proposed occupancy;
ceiling heights and how much floorspace beneath sloping roofs can count.
Applying these standards takes more than measuring rooms. The size of a bedroom may depend on the communal facilities available, while its shape, windows and furniture layout affect whether the space is usable. Greenwich’s HMO standards, for example, distinguish between different arrangements of bedrooms, kitchens and shared living rooms.
These choices need testing together before fixing the bedroom count. Enlarging one room may leave too little communal space; adding a bathroom may compromise circulation or escape.
An experienced HMO architect can work through those trade-offs to establish a suitable layout and occupancy for your HMO conversion, rather than discovering after submission that rooms meeting the licensing minimum still fall short of planning requirements.
These are the points London councils and Planning Inspectors test most often. Each needs to be shown on the drawings or backed by evidence, not simply asserted in a planning statement.
Let the layout set the number of residents: fix occupancy after testing the layout, not before. Five comfortable rooms with a usable living room often perform better, at application and in management, than six rooms with nowhere to sit together.
Size shared space to the residents: kitchens, bathrooms and living space must match the number of people, and many boroughs set ratios and minimum sizes in their HMO standards.
Treat bedroom size as the start of the test: a room that meets the minimum floor area can still fail on outlook, daylight, privacy, ceiling height or usable shape. Back any room with a constrained window with a daylight assessment.
Check what an extension does to the rooms behind it: added floorspace can remove the light that makes another room habitable.
Route activity away from neighbours: entrances, side passages, bins and bicycles near a neighbour's windows or door are where disturbance objections start. A management plan helps, but it cannot move a door.
Make cycle and bin storage reachable: show the route from the street to the store, without bicycles being carried through the kitchen or living room.
Give every bedroom a safe escape route: London Plan Policy D12 applies to all development, and an escape route through a kitchen or living room can decide an appeal.
Evidence flood safety early: most changes of use avoid the sequential test, but in Flood Zones 2 and 3 a proportionate flood risk assessment and safe sleeping accommodation are still required.
Secure car-free status properly: where the borough expects permit-free development, agree the legal mechanism with the council before submission.
Together, these checks establish whether the proposed occupancy works for residents, neighbours and the property itself. Leaving them unresolved can undermine an otherwise acceptable scheme: many common reasons councils refuse HMO planning applications arise from details that needed resolving through the design and supporting evidence before submission.
An HMO conversion budget includes professional fees, council charges, specialist reports and building work. The total depends on the property’s condition, the proposed occupancy and how much alteration is needed.
The programme also extends beyond the council’s usual eight-week decision period. Surveys, design, supporting reports, planning conditions and construction all need allowing for before the property is ready to let.
The main fees under the government’s 2026 fee schedule are:
Professional fees, specialist reports and any Planning Portal submission charge are additional. Applications required because of an Article 4 direction still attract a fee, and revised applications generally require payment again.
Draft regulations propose increasing the HMO change of use fee to £732 from 8 December 2026, an increase of £122. This remains subject to the regulations being approved and brought into force.
Every HMO application needs a core set of work:
a measured survey of the existing building;
existing and proposed plans, elevations and sections, with room areas and occupancy shown;
a Design & Access statement that addresses the borough's HMO policy and standards;
cycle and refuse storage details, including the route to them;
a draft management plan and a proportionate fire safety statement.
Other evidence depends on the site, and it is where budgets most often grow:#
Your architects and town planners should identify which reports are needed, explain the costs and coordinate the specialists. Their role is to turn those findings into a better HMO design and a well-supported planning case, addressing potential objections before the application is submitted.
Many chartered architectural practices and town planning consultancies charge from £5,000+VAT to prepare an HMO planning application. This is also the starting fee for our services at Urbanist Architecture, covering drawings and statements, consultant coordination, submission and liaison with the council. Fees rise with the property’s size, proposed occupancy, planning constraints and complexity.
Across the wider market, the quotations I see range from about £3,000 to £10,000. Understanding that difference means looking beyond the price to the work included and the experience behind it. For an HMO, the quality of the design and the strength of the planning case depend on each other.
As chartered architects and town planners, we develop both together. Bedroom arrangements, communal space and effects on neighbours need resolving through the layout; a well-written statement cannot make an unsuitable design acceptable.
That is why relevant HMO decisions, qualifications and professional indemnity insurance deserve checking before you appoint anyone. Missed restrictions or poorly resolved layouts can lead to refusal, further fees and months of lost rental income. Chartered status does not guarantee permission, but it provides a basis for professional accountability. Where low fees are the main selling point, consider what the initial saving could cost later.
Experience can also reveal opportunities. A carefully developed layout may accommodate an additional bedroom while meeting planning requirements and providing good living conditions. For your investment, that extra capacity may be worth considerably more over time than a couple of thousand pounds saved on professional fees.
An HMO application follows the same planning application process as any change of use, but the decision is only one of five stages:
Preparation: confirming the lawful use and Article 4 position, the survey, design options and any site-specific reports. Third-party inputs, such as Environment Agency flood data, often set the pace.
Validation: the council checks the submission against its local validation list. The eight-week period does not start until the application is valid, so missing information delays the clock before it begins.
Determination: eight weeks for a change of use or a lawful development certificate, unless you agree a longer period in writing. If a planning application is undecided after 16 weeks without an agreed extension, the fee is refunded; certificates are not covered by that guarantee.
Conditions: each request to discharge conditions has its own eight-week period, and pre-commencement conditions must be cleared before work starts.
Implementation: building regulations approval for the works, the HMO licence where one is required, and occupation only once pre-occupation conditions, such as cycle and refuse storage, are discharged.
The statutory target and the elapsed time are different measures. Eight weeks is the decision period for one stage, and actual planning permission timelines in London vary widely between boroughs.
From 31 October 2026, a national scheme of delegation makes officers the default decision-makers for most smaller applications. The regulations do not say expressly how an HMO change of use is classed, and retrospective applications can still be referred to committee in limited cases.
A refusal is disappointing, but it does not always mean the end of the proposal. HMOs have a reputation for being difficult to get through planning, yet the next step depends on why the council said no. Several common refusal reasons for HMO planning applications concern layouts, living conditions or missing evidence that may be addressed in a revised scheme.
Your architect and town planner should work through the decision notice before recommending a response. Sometimes, redesign and a fresh application offer the clearest route, although another application fee is payable. Where the disagreement concerns policy interpretation or the council’s assessment of the evidence, a planning appeal may be appropriate.
For a refused change of use, the appeal must normally be lodged within six months of the decision notice. Enforcement cases can have shorter deadlines, so check the applicable time limit immediately.
For applications made on or after 1 April 2026, most appeals follow a written procedure that does not accept new evidence or amended plans. This makes a complete, well-supported application important from the outset.
Appeals also add time. In the 12 months to June 2026, those decided by written representations took a median of 16.4 weeks, according to the Planning Inspectorate’s statistics.
Some published guides suggest £40,000–£75,000 for a lighter HMO conversion in London and £90,000–£150,000 for a more extensive scheme. Treat these ranges carefully: a limited refurbishment involves far less work than a full five-bedroom conversion.
Drawing on our experience of dozens of HMO conversions across London, we would allow at least £130,000 as an initial construction budget for a full five-bedroom scheme.
The cost goes beyond kitchens, bathrooms and decoration. Meeting the applicable Building Regulations and HMO requirements may involve fire protection, improved escape routes, sound insulation, ventilation, drainage and upgrades to plumbing and electrics. Underestimating these works before buying can undermine the project’s viability.
Replacing services, altering the structure or adding several en-suites can push costs higher. Extensions and loft conversions add further expense. The building’s condition and the proposed specification therefore matter more than a generic price per bedroom.
At RIBA Stage 4, your architect prepares technical drawings and specifications for the tender package, allowing contractors to price a clearly defined scope. Without this detail, a low quotation may omit essential work that later appears as costly extras. Look closely at what each contractor has included and how carefully they have reviewed the package, alongside the price.
Our work across London and the rest of the country ranges from small HMO conversions to co-living schemes of up to 26 rooms. Across these projects, we often encounter the same assumption: that a licence, a seller’s description or a neighbour’s conversion means the planning position is settled.
As chartered architects and town planners, we begin with property due diligence, checking the lawful use, Article 4 restrictions and the council’s requirements. We then test what the property can comfortably accommodate, considering bedrooms, shared spaces, daylight, outlook and effects on neighbours together. For flats, lease restrictions also need checking separately.
We use those design decisions to build the planning case, showing how the proposal meets local requirements, addresses the site’s constraints and draws on support for housing under the NPPF 2026.
Our role is to establish a credible planning route and realistic occupancy before you exchange or start work, so your purchase and conversion budget are grounded in what the property can lawfully and comfortably accommodate.
We look forward to learning how we can help you. Simply fill in the form below and someone on our team will respond to you at the earliest opportunity.
The latest news, updates and expert views for ambitious, high-achieving and purpose-driven homeowners and property entrepreneurs.
We specialise in crafting creative design and planning strategies to unlock the hidden potential of developments, secure planning permission and deliver imaginative projects on tricky sites
Write us a message