Read next
The latest news, updates and expert views for ambitious, high-achieving and purpose-driven homeowners and property entrepreneurs.

Imagine you own a four-bedroom 1930s semi in London. A letting agent estimates that a family would pay £2,600 a month to live there.
Then you explore letting it room by room. Four rooms at £1,000 each could bring in £4,000 a month. Extend the house to create seven rooms, each achieving the same rent, and the potential income rises to £7,000. That is more than two and a half times the family rent.
The appeal is clear. Even the four-room option could generate an extra £1,400 a month before costs. How much you retain will depend on management, maintenance, finance, any bills included in the rent and periods when rooms stand empty.
The seven-room scheme offers greater rental potential, but getting there takes money and time. If the extension and conversion cost £240,000 and leave the property empty for a year, you would need to fund the works while forgoing £31,200 in gross rent from a family let. The finished property must earn enough to justify that commitment.
This is where planning and design become central to the investment. Article 4 directions and local conversion policies help determine whether the proposal can proceed. The layout, room sizes and shared facilities influence how many people the property can comfortably accommodate, its appeal to tenants and the rents it can achieve.
Successful House in Multiple Occupation (HMO) property investment means bringing these decisions together before committing money. In this article, I will explain how to assess rental potential, establish lawful occupancy, develop a good layout and consider future resale, helping you choose a viable scheme that provides good accommodation and a worthwhile return.
A house in multiple occupation (HMO) is generally a house or flat rented to at least three people from two or more households who share a kitchen, bathroom or toilet. A household can be one person, a couple or members of the same family living together. For example, three unrelated friends sharing a rented house would usually form three households.
Unlike a conventional buy-to-let occupied by one household, an HMO is often let room by room. This can generate more rental income from the same property, but the return depends on conversion costs, ongoing expenses and how well the accommodation is designed and managed.
In planning terms, a small HMO houses three to six residents and falls within Use Class C4. A larger HMO accommodating more than six residents normally falls outside the use classes and is described as sui generis.
Converting a family house (Class C3) into a small HMO normally benefits from permitted development rights. You need planning permission for an HMO where a relevant Article 4 direction removes that right or another restriction prevents its use. Converting a family house into a larger HMO normally requires a planning application, whether or not an Article 4 direction applies.
These thresholds concern residents, not bedrooms. A couple sharing a room counts as two residents. If you are buying or enlarging an existing HMO, establish its lawful use and check any occupancy conditions before assuming it can accommodate more people.
Extensions and other building works also need a separate assessment of their planning and Building Regulations requirements.
HMOs are not only a profitable investment opportunity for landlords, but they also serve a critical role in the UK rental market by providing flexible, affordable housing solutions for a wide range of tenants.
With astronomical rental prices making traditional one-bedroom flats unaffordable for many, HMOs offer a cost-effective alternative where tenants can rent a private room while sharing communal facilities such as kitchens, living areas, and bathrooms.
This setup particularly benefits young professionals, students, and low-income renters who may not be able to afford self-contained flats but still seek high-quality accommodation.
So who exactly are HMOs for?
These groups do not all want the same accommodation. Someone working shifts may place particular value on acoustic privacy, while someone working from home may need a usable desk and reliable broadband.
Choose the intended tenant group before fixing the specification. Understanding what residents need gives the design and rental appraisal a clearer foundation.
Yes. Letting rooms individually can produce a higher total rent than letting the same house to a family. The opportunity is strongest where there is demand for shared accommodation and the building can meet that demand without disproportionate conversion work.
SpareRoom’s Q3 2026 figures put average asking room rents, including bills, at £1,002 a month in inner London and £800 in outer London. These are broad benchmarks, not evidence of what a particular room will achieve.
Returning to the house in our opening example, suppose you also test a six-bedroom conversion as an alternative to the seven-room extension. For this illustration, assume the layout can provide six comfortable bedrooms and suitable shared facilities. The family letting option remains £2,600 a month, excluding bills.
If the property could lawfully accommodate six residents, each paying £1,000 a month including bills, it would generate £6,000 a month. That is £72,000 in gross annual HMO rent, compared with £31,200 from the family let: an additional £40,800 a year.
These illustrative figures assume full occupancy and one resident per HMO bedroom. They show the potential increase in rental income, before accounting for the HMO’s higher expenses and the investment needed to create it.
To assess whether conversion is worthwhile, compare the additional income retained after running costs with the complete investment required.
Allowing 5% for periods without tenants reduces annual rent collected to £29,640 for the family let and £68,400 for the HMO.
Now assume annual operating expenses of £6,000 for the family let and £22,000 for the HMO. Both budgets cover management, repairs, insurance and compliance. The HMO allowance also includes utilities, broadband, Council Tax and communal cleaning, consistent with its bills-inclusive rents.
This leaves £23,640 a year from the family let and £46,400 from the HMO, before finance and tax. The HMO therefore retains an additional £22,760 a year.
These are illustrative allowances, rather than standard operating budgets. Check actual costs against the property, intended occupancy and management arrangements before relying on the comparison.
For the alternative six-bedroom scheme, suppose the initial construction allowance is £150,000. This is a separate illustrative budget from the £240,000 seven-room extension introduced earlier. Measured drawings and an assessment of the building’s condition would establish the work each option requires.
Professional fees at many chartered architectural practices and planning consultancies start from £5,000+VAT for preparing an HMO planning application. Your wider budget should also cover surveys, specialist reports, council charges, technical design, Building Regulations approval, licensing where required and furnishing.
Include applicable VAT, contingency, borrowing and holding costs, and rent forgone while the property is being prepared and converted.
A house that already lends itself to shared living may need relatively modest alterations. If creating the proposed accommodation requires extensive work, the additional rental income must justify that larger commitment. Testing layout options early helps you identify where investment will improve the accommodation and where it may add cost without sufficient benefit.
In parts of London, yes. Councils are tightening controls over HMO conversions following residents’ concerns about the loss of family homes, concentrations of shared housing, noise, rubbish and parking pressures.
For example, Harrow introduced new controls in June 2026, while Lambeth introduced restrictions in two Streatham wards in August 2025. These changes bring more conversions into the planning system, giving councils greater control over where HMOs are created and the accommodation they provide.
Research assembled by Urbanist Architecture found that applications for planning permission for an HMO across London almost doubled, from 754 in 2023 to 1,460 in 2025. These included proposals to create new HMOs and expand existing ones.
Yet approval rates remained broadly between 40% and 45% across the years examined. Growing investor interest has not translated into easy approvals: fewer than half of the applications receiving an approval or refusal secured permission.
The research covered applications received between January 2019 and June 2026. Approval rates reflect council decisions before appeal and exclude withdrawn and undecided applications.
For investors, the message is clear: establish whether the property offers a credible planning opportunity before committing to its conversion. Understanding the relevant planning policies for HMO conversions in London is central to that decision.
Councils may assess the property’s original floor area, the loss of family housing, nearby HMO numbers and access to public transport and services. These tests can determine whether conversion is acceptable before the detailed layout is considered.
An extension needs particular care. Where a policy measures the house as originally built, adding floorspace may improve the accommodation without resolving the underlying policy objection.
A successful planning strategy starts with identifying what the council needs to be satisfied about. Our role as architects and town planners is to connect those requirements with a workable design, an appropriate number of residents and supporting evidence that addresses the proposal’s effects.
That means testing more than bedroom numbers. Daylight, shared facilities, neighbouring homes, acoustic privacy, waste storage and cycle access all contribute to a convincing application. Resolving these matters together produces a stronger proposal than fixing the layout first and trying to justify it afterwards.
Our enquiries also include HMO schemes that have already been refused permission. We review the submitted drawings, supporting documents and reasons for refusal to establish whether the decision should be challenged or the proposal improved.
Where the design and evidence support the case, an appeal may be the appropriate route. Where the objections reveal shortcomings, we may recommend revising the layout, reducing occupancy or strengthening the evidence before submitting a fresh application.
The expertise lies in distinguishing an objection that can be contested from one that calls for a better scheme. Making that judgement early helps HMO investors direct their budget towards the route with the strongest prospects and accommodation that will work well once occupied.
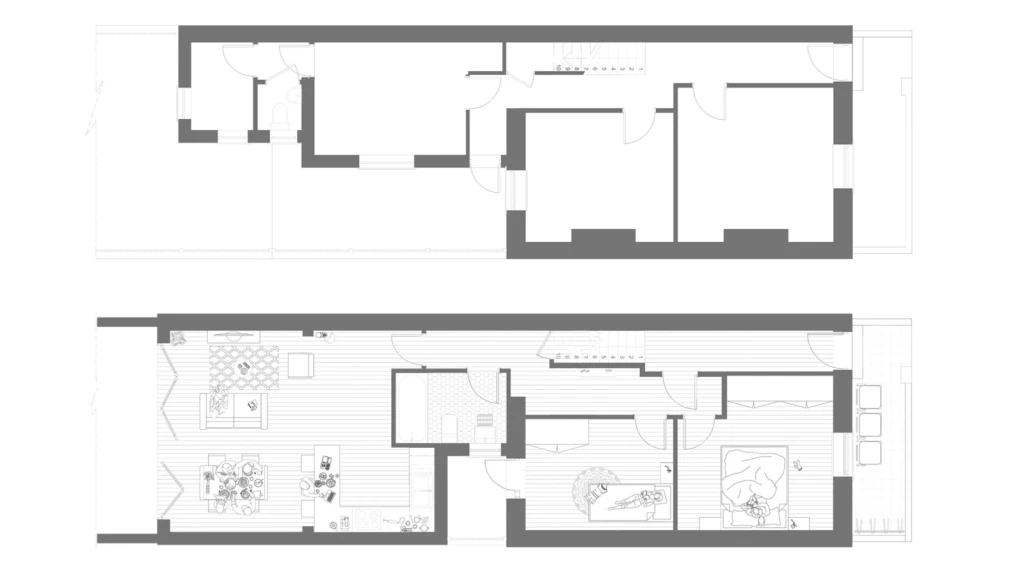
Good design can address relevant planning concerns while creating accommodation tenants find attractive. The strongest layout gives every resident a usable private room and makes the shared parts of the house comfortable in daily use.
Position bedrooms around the windows and outlook the house can provide. Check room depth, ceiling height and the space remaining once a bed, wardrobe and desk are shown properly on the plan.
A nominally large room can be awkward to furnish, while an extension can deprive an existing bedroom of useful light. Plans and sections should test those relationships together; constrained rooms may need daylight evidence before an application is submitted.
For the investor, this establishes whether a room can credibly form part of the rental offer. A bedroom that depends on an unacceptable outlook or unresolved lightwell is an uncertain income assumption, however neatly it fits on a spreadsheet.
Residents may rent their bedrooms separately, but they share the consequences of the layout. A kitchen needs enough preparation space, storage and facilities for the intended occupancy, with room to move when other people are cooking.
A comfortable dining or living area gives residents somewhere to eat, socialise or spend time away from their beds. It also helps the drawings demonstrate that the house can accommodate the proposed number of people.
Turning the lounge into another bedroom changes the accommodation offered to every resident. It adds one source of rent, but removes shared space from the rest of the household. Some borough standards also require larger bedrooms where separate communal space is unavailable.
Compare the layouts as complete homes. Would the additional bedroom leave enough space for everyone to cook, eat and relax? Would the other rooms remain equally attractive to tenants? Would the change introduce planning objections or require further building work?
This brings us back to the seven-room option in the introduction. The seventh room earns its place when its additional rent justifies the work and the whole house still provides comfortable, acceptable accommodation. Assessing that room means assessing its effect on the entire investment.
Bathroom provision should suit the residents and their routines. Consider where facilities sit, how people reach them and whether extra plumbing or ventilation will compromise another room.
En suites may appeal to the intended tenants, but they consume space and add installation and maintenance costs. Compare their benefit with larger bedrooms and well-arranged shared bathrooms before specifying one in every room.
Storage deserves the same attention. Space for clothes, food, cleaning equipment and household supplies helps keep bedrooms usable and communal areas clear. Built-in storage should improve the layout without making a room too tight to furnish comfortably.
Consider how bedrooms relate to kitchens, bathrooms, stairs and neighbouring homes. Sensible room placement and appropriate acoustic separation can improve privacy and help address concerns about disturbance.
That matters to the rental offer as much as the planning case. A bedroom beside an active kitchen needs more thought than a promise that residents will be considerate.
Specify durable, repairable finishes for the intensity of shared use. Robust kitchen fittings, suitable flooring and accessible service components can make maintenance easier and help the accommodation remain presentable between lettings. Spending on surfaces that photograph well but deteriorate quickly offers less lasting value.
Show where waste and bicycles will be stored and how residents will reach them. A correctly sized cycle store is of little practical use if the only route requires carrying bicycles through the shared kitchen.
Resolve these arrangements alongside entrances, boundaries and neighbour relationships. A workable storage strategy helps the house function and provides evidence for the application; leaving it until the bedrooms are fixed may require a costly redesign.
Several common reasons HMO applications are refused begin with these unresolved relationships. Better design can improve a proposal’s prospects, but it cannot overcome every policy objection or guarantee permission.
A successful HMO should suit your longer-term plans as well as its first letting. Establish how the property is likely to be funded, valued and sold before the conversion fixes its layout.
Selling with vacant possession also requires an appropriate tenancy and possession strategy. The Renters’ Rights Act changes from May 2026 mean Section 21 is abolished and most private assured tenancies are periodic. Keep planning, building control and licensing records organised, and remember that an HMO licence cannot transfer to the buyer.
A promising property combines a credible planning route, local tenant demand and a building that can accommodate shared living comfortably.
Start with the location and the borough’s policies. Access to employment, education, shops and public transport can support demand, while local tests on family housing, HMO concentration or accessibility may determine whether conversion is acceptable.
Then examine the building’s proportions, windows, stairs, drainage and access. A deep floor plan may appear to offer ample bedroom space but provide poor daylight. A narrow terrace may lack a practical route to rear cycle storage. Well-positioned windows and stairs can make a comfortable layout easier to achieve.
Look for opportunities to improve shared accommodation as well as add bedrooms. A modest extension that creates a generous kitchen and dining area may improve the whole house. Before buying, establish whether the garden, access and building arrangement allow that improvement without creating new difficulties elsewhere.
Compare what the existing building can comfortably accommodate with any more extensive proposal. An extra bedroom strengthens the investment only if its rent justifies the work and the remaining accommodation still serves residents well.
The best purchase is one whose planning position, physical layout and conversion budget support the rental income you expect to achieve.
Resolve the uncertainties that could change the purchase or design decision while there is still room to respond. An architectural feasibility assessment should connect the planning position with measured layout options, rather than simply produce the greatest possible bedroom count.
Establish the lawful use, Article 4 position and relevant local policy before paying for assumed HMO potential.
Test bedrooms, shared space, safe escape and servicing together, so the proposed occupancy is credible.
Check achieved local rents and the accommodation those rents reflect, then price the work and ongoing operation.
Confirm the funding and intended exit before committing to alterations that would be difficult to reverse.
Where a specific planning uncertainty remains, pre-application advice can be useful once a measured proposal shows what is intended and how it would work.
If the evidence supports the conversion, proceed with a coherent brief. If the house cannot meet a decisive policy test, or the required work undermines the investment, change the proposal or reconsider the purchase before further expenditure becomes difficult to recover.
The HMO model has evolved far beyond the outdated stereotype of overcrowded student digs. Its potential lies in combining attractive rental income with well-designed, professionally managed accommodation.
The wider rental market is evolving too. Purpose-built student accommodation, larger co-living developments, short-term let aparthotels and serviced apartments offer different approaches to accommodation, service and flexibility. Their scale, operation and planning treatment differ, but they give HMO investors useful ideas about what residents value and how to distinguish their own offer.
For owners converting a house into an HMO, the opportunity is to bring that thinking to a smaller, more personal setting, with comfortable private rooms, inviting shared spaces and reliable management. As the sector develops, so too must the mindset of investors.
Here are six developments worth watching over the next five to ten years, and how to prepare for the opportunities they could create.
Expect planning restrictions, licensing requirements and accommodation standards to remain central to HMO investment. Their effect will differ between councils, making local knowledge increasingly valuable.
Rather than treating these requirements as obstacles alone, informed investors can use them to distinguish credible opportunities from speculative ones. Where new conversions are restricted, an existing HMO’s documented lawful use may become more important to buyers.
Owners who make compliance part of their investment strategy will be better placed to manage change and avoid preventable disruption.
Purely functional shared housing leaves room for a better offer. Tenants, particularly young professionals, want homes that feel comfortable and personal rather than institutional.
HMOs with considered design, suitable bathroom provision, flexible working spaces and thoughtful communal areas can support stronger rents and encourage residents to stay, where local demand justifies the investment.
The next opportunity is to design around different daily routines. A kitchen that accommodates simultaneous cooking, somewhere to take a work call and acoustic separation between social and sleeping spaces can offer more everyday value than expensive finishes.
The strongest proposition will not necessarily contain the most rooms. It will make the available space work better for the people sharing it.
Where renting a self-contained home is beyond someone’s budget, good shared accommodation offers a practical alternative.
That gives HMOs a continuing role in urban locations serving students, graduates, key workers and people relocating for employment. The opportunity is to offer affordability without making poor living conditions the price residents pay for it.
Demand will still vary by location, rent and tenant group. Investors who understand those differences can develop a clearer offer than those who assume any room in a busy city will let.
National ambitions for housing delivery and more efficient use of existing buildings do not translate into the same HMO opportunities everywhere.
Local policies on family housing, concentration and accessibility will continue to shape which properties are suitable. Emerging plans may change the investment case before an owner is ready to submit an application.
Investors who track those changes and engage with planning professionals can identify promising locations earlier and avoid buying against a policy direction they have overlooked.
The advantage lies in understanding where a credible planning route and a suitable building coincide.
Purpose-built co-living offers a different scale of shared accommodation, with coordinated design, branding and management. Its influence may raise expectations of what shared living can provide.
Smaller landlords need not copy its facilities to compete. Their opportunity is to offer something different: a smaller household, a distinctive existing house and communal spaces that feel domestic rather than anonymous.
Those who combine these qualities with reliable management can create a compelling alternative. Modernisation should strengthen what makes the property appealing, rather than add features whose cost the local market will not support.
Managing one HMO manually is time-consuming. Managing several without reliable systems makes it harder to keep track of repairs, inspections, payments and operating costs.
Cloud-based management tools, utility tracking and automated administration can help landlords organise that work and expand more confidently.
The greater opportunity is to recognise patterns. Repeated condensation, unusually high energy use or recurring repairs can reveal weaknesses in ventilation, controls or specification, helping owners direct improvement budgets where they will be most useful.
The future of HMO investment will favour owners who combine vision with discipline and adaptability. Well-chosen properties, thoughtful design and attentive management can create shared homes that serve residents well while supporting a resilient rental business.
Our exploration of HMO developments concludes, but your journey toward creating an exceptional shared living space is just beginning.
With more than 900 completed projects in our portfolio, including every conceivable type of property conversion, we've witnessed firsthand how thoughtfully designed HMOs consistently deliver impressive annual returns. The planning strategies and design principles that have proven successful for our clients are readily adaptable to most properties across a wide range of London boroughs.
If you wish to partner with specialist HMO architects who truly understand both the regulatory landscape and the design elements that create comfortable, profitable HMOs, we're here to translate your investment vision into architectural reality.
However, our expertise is reserved for those serious about creating quality HMOs, not landlords seeking to cut corners or compromise on standards. If you share our commitment to exceptional design and are prepared to invest appropriately in your project, we invite you to contact us to explore a potential collaboration.
We look forward to learning how we can help you. Simply fill in the form below and someone on our team will respond to you at the earliest opportunity.
The latest news, updates and expert views for ambitious, high-achieving and purpose-driven homeowners and property entrepreneurs.
We specialise in crafting creative design and planning strategies to unlock the hidden potential of developments, secure planning permission and deliver imaginative projects on tricky sites
Write us a message